Crossing state lines with inherited and gifted firearms

giftI received an email today from a client who had a question about receiving firearms from an out-of-state relative. He wanted to make sure that the transfer was conducted legally under federal law as well as the laws of both Virginia and the other state.

In his case, since neither the other state nor Virginia impose any legal requirements upon the private gifting of firearms (other than the recipient not be a prohibited person), we are just dealing with an issue of purely federal law.

However, his particular situation was complicated somewhat by the fact that the gift was occurring subsequent to the death of a family member.  His uncle had passed away and his aunt had offered to give him his uncle’s handguns.

When he called the state police in his aunt’s state of residence, they told him that he should just pick up the handguns and drive them back to Virginia.  They said that since this was an inheritance, federal law allowed a direct interstate transfer.

The problem?  This was not an inheritance!  His uncle had left his entire estate to his aunt.  His aunt, lacking interest in the shooting sports, was making a gift of the items to my client.  Therefore, the ‘inheritance exception’ to the federal prohibition on interstate transfers does not come into play.

So how should interstate gifts of firearms be handled?  Let’s start by looking at federal law.

18 U.S.C § 922 (a)(3) starts off by giving us the general rule that it is illegal “for any person, other than a licensed [party] to transport into or receive in the State where he resides … any firearm purchased or otherwise obtained by such person outside that State.

However, there are a number of exceptions to the general rule.  The first exception is for “any person who lawfully acquires a firearm by bequest or intestate succession in a State other than his State of residence … if it is lawful for such person to purchase or possess such firearm in that State.” 

This is the exception that my client initially believed might apply to his situation. However, this exception requires that the person acquire the firearm by ‘bequest or intestate succession‘ and neither was the case here.  A gift from an executor does not satisfy this requirement.

Therefore, to comply with the requirements of federal law, a person receiving a gift of firearms from out-of-state should have the person giving the gift ship the firearms to a Virginia FFL where the recipient can proceed with the transfer process.

A final note:  There is also an exception for rifles and shotgun which requires that the transfer “fully comply with the legal conditions of sale in both such States.”  Since an analysis of the various laws of all 50 states goes far beyond the scope of this article I will simply note that the exception exists.
Posted in Estate Planning, Federal Law, Gifting Firearms, Interstate Firearm Transfers, Interstate Travel, Virginia Law | Comments Off on Crossing state lines with inherited and gifted firearms

Is a background check required when picking up NFA items from a dealer for a trust?

Yes-No-MaybeOver the last two days I have been asked this question multiple times.  It seems that there is a great deal of confusion over this issue among both NFA owners and dealers.
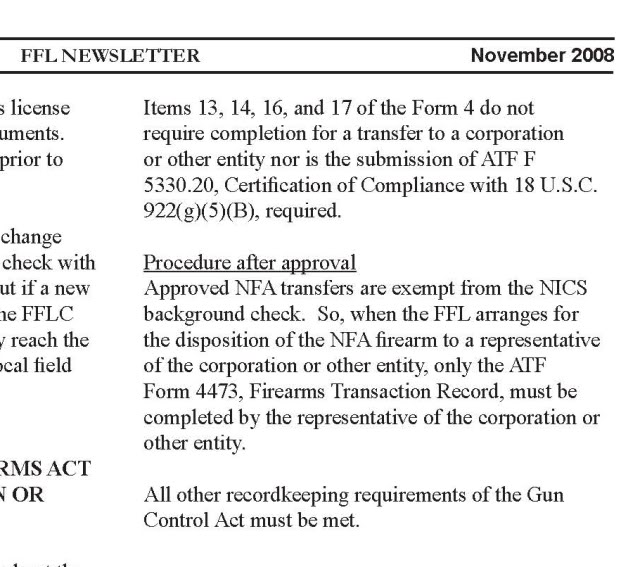
However, I do not say this to disparage those who are confused.  Many of those who believe that a background check is not required base that belief upon information provided by the ATF themselves.  For example, they clearly stated that background checks were not required in a 2008 FFL Newsletter.

08_FFL_Newsletter

However, since the publication of that newsletter, the ATF has drawn a nuanced legal distinction between an individual owner picking up an NFA item subsequent to an approved tax stamp and a trustee of a trust doing the same.

In March of 2014 the ATF explained the statutory and regulatory basis for this new distinction in the following letter to Dakota Silencer.  Pay specific attention to the first two paragraphs on the second page.

Download (PDF, 128KB)

In September of 2014 the Virginia State Police followed up with their own guidance to dealers.  While poorly worded it does reiterate and support the ATF’s logic from the Dakota Silencer letter.

VA_Trust_SP65

So … the answer is “Yes” … if the tax stamp for the NFA item you purchased using an NFA trust has been approved and you are heading down to the dealer to pick it up, you will have to complete both a 4473 and a SP-65 and undergo a background check.

Posted in 4473, ATF, ATF Guidance Letters, Background Checks, BATFE, Federal Law, FFL 03, FFL Issues, NFA Transfers, NFA Trusts, SP-65, Virginia State Police | Comments Off on Is a background check required when picking up NFA items from a dealer for a trust?

Delegate Webert introduces bill to recognize other state’s gun rights restorations

50_States_PuzzleBack in September of 2014 I wrote an article entitled Gun rights restoration is a state-by-state process.
In that article I demonstrated that generally, “a gun-rights restoration in a given state only allows you to purchase, possess, and transport firearms in that state.

I believe it is safe to say that article generated more phone calls from concerned clients than any other single article I have ever written.

The most common conversation went something like this:

Client: “I had my rights restored in Virginia 15 years ago.”

Me:  “Ok.  That removes both your Virginia and federal prohibitions.”

Client: “And I have a Virginia concealed handgun permit.”

Me:  “Good.”

Client: “And the Virginia permit is recognized in North Carolina.”

Me:  “Yes it is.”

Client: “And I assumed I could carry in North Carolina.”

Me: “Ummm …. no you cannot!”

While  legislation inVirginia cannot do anything about making other states recognize our rights restoration process, we can take steps to codify the requirements for rights restorations from other states to be recognized in the Commonwealth.

Delegate Webert’s bill HB 2286 does just that.  It removes Virginia’s prohibition on firearms ownership for those felons “whose right to possess firearms or ammunition has been restored under the law of another state or political subdivision thereof.”

Posted in Gun Rights Restoration, Interstate Travel, Non Resident Issues, Virginia Law | Comments Off on Delegate Webert introduces bill to recognize other state’s gun rights restorations

Is the $200 tax on an NFA item deductible on your federal return?

TaxesIt is the start of a new year, and many of us are reluctantly turning our attention to the filing of taxes.
That was certainly the case for the client who emailed me this morning and asked whether or not the $200 excise tax that is paid pursuant to the manufacture or transfer of an NFA item is deductible on his federal return.

It is definitely a valid question.  After all, certain other taxes represent deductions from your federal return.  Why not the NFA transfer tax?

Let’s take a closer look at the tax statutes.

26 U.S. Code § 164 tells us which taxes are deductions for purposes of your federal return. These include

(1) State and local, and foreign, real property taxes.
(2) State and local personal property taxes.
(3) State and local, and foreign, income, war profits, and excess profits taxes.
(4) The GST tax imposed on income distributions.
(5) The environmental tax imposed by section 59A.
(6) Qualified motor vehicle taxes.

This code section goes on to note that “any tax (not described in the first sentence of this subsection) which is paid or accrued by the taxpayer in connection with an acquisition or disposition of property shall be treated as part of the cost of the acquired property.

In addition,the IRS specifically mentions ‘stamp taxes’ in their Tax Topics page on deductible taxes .

Some taxes and fees you cannot deduct on Schedule A include federal income taxes, Social Security taxes, transfer taxes (or stamp taxes)

So … while I always encourage my clients to take all deductions and exemptions for which they are legally eligible, that stack of canceled checks to the BATFE isn’t one of them.

Posted in ATF, BATFE, Federal Law, IRS, NFA Transfers, Tax Stamp | Comments Off on Is the $200 tax on an NFA item deductible on your federal return?

What are the requirements for engraving an item you are building on a Form 1?

Engraving

This is one of those questions that gets asked over and over again and I should have written about it long before now.

But today I correct that omission.

Let’s walk through this in 10 easy steps.

1)  When you build an NFA item subsequent to a Form 1 approval, you are legally the ‘manufacturer’ of the resulting NFA item even if it is built upon an existing serialized lower.

2)  27 CFR 478.92 and 27 CFR 479.102 both lay out the requirements for placing identifying markings on items you ‘manufacture’.

3)  These regulations require that you engrave a serial number, model (if applicable), caliber or gauge, manufacturer’s name, and the city and state where the item was ‘manufactured’.

4)  If you are using an NFA trust to hold your NFA items then the trust name is the manufacturer’s name you will need to engrave.  If not, you will need to engrave your full legal name as the manufacturer.

5)  When you ‘manufacture’ an SBR or SBS using an existing lower the ATF allows you to ‘adopt’ the serial number, caliber/gauge, and/or model already identified on the lower if the lower meets or exceeds the marking requirements.  See ATF Ruling 2013-3 embedded below.

6)  The marking may be engraved, cast, or stamped.

7)  All markings must be to a minimum depth of .003 of an inch as measured from the flat metal surface.

8)  The serial number must be in a print size no smaller than 1/16th of an inch.

9)  There is no specific statutory or regulatory height requirement for the remaining information other than it be ‘legible’.  However, most NFA collectors choose to engrave the manufacturer’s name, city, and state in a 1/16th print size as well.

10)  Laser engraving is an amazing process and can result in beautiful work on your firearm but make sure that any laser engraving shop you select is capable of meeting the depth requirements above.

ATF Ruling 2013-3 allows for the ‘adoption’ of existing markings

Posted in 80% Lower, ATF, BATFE, Engraving, Form 1, Manufacturing, NFA Trusts, SBR, Short Barreled Rifles, Short Barreled Shotguns | Comments Off on What are the requirements for engraving an item you are building on a Form 1?